S&P 500 Investing Explained: A Simple Guide for Busy Newcomers
The first time I heard someone talk about the S&P 500, it sounded like a secret code, or a members-only club that only Wall Street insiders were allowed to join.
When you are focused on building a stable life in a new country, financial terms like “indexes,” “tickers,” and “large-cap benchmarks” feel completely disconnected from daily reality. You are learning a new system, sending money home, paying rent, and maybe working two jobs. When every dollar counts, putting your money into something you do not fully understand feels like an unnecessary gamble. That instinct is smart. You should never invest in something you cannot explain.
So let’s explain it. The S&P 500 is not an exclusive club or a complicated financial product. It is a list of 500 of the largest publicly traded companies in the United States, and investing in it is one of the most widely recommended ways to grow wealth over time without spending hours studying the stock market. By the end of this guide, you will know what it is, why so many people use it, and exactly how to buy it, even if you are starting with a small amount.
What the S&P 500 Actually Is
Imagine walking into a massive shopping mall that houses the biggest businesses in America. Instead of trying to guess which individual store will thrive this year, you buy a tiny share of all of them at once. That is the idea behind the S&P 500.
The index is maintained by S&P Dow Jones Indices, and a committee selects the companies in it. To qualify, a company generally needs to be based in the US, be large enough, trade actively, and be consistently profitable. Together, these 500 companies represent roughly 80% of the value of the entire US stock market.
Here is the part that confuses many beginners: the S&P 500 itself is not something you can buy. It is a list, a scoreboard. What you buy is an index fund or ETF that copies that list. When you buy one, you instantly own a microscopic piece of household names like Apple, Microsoft, Amazon, Google, and hundreds of other businesses, from banks and hospitals to grocery suppliers and energy companies.
You do not need to choose winners or losers. If one company struggles, its impact on your total investment is limited because your money is spread across the other 499. If you want a broader foundation first, start with our guide on what investing is and why it matters, or read the beginner’s guide to the stock market.
Index fund vs. ETF: what’s the difference?
You will see both terms, and for a beginner the difference is small. An ETF (exchange-traded fund) trades on the stock market like a share, so you can buy it any time the market is open. A traditional index mutual fund is priced once per day after the market closes. Both track the same list of companies. Pick whichever your brokerage makes easiest, and don’t let this choice slow you down.
Why the S&P 500 Works Well for Busy People
Newcomers and busy professionals share one big constraint: very little free time. Between demanding work schedules, family responsibilities, and adapting to a new culture, spending weekends analyzing corporate balance sheets is out of the question. The S&P 500 solves much of that problem.
1. Built-In Quality Control
The companies in the S&P 500 are not chosen at random, and they are not permanent members. When a company shrinks, loses profitability, or no longer meets the requirements, it can be removed and replaced by a stronger, growing company. The index refreshes itself over time, so you are not forced to research which businesses to keep or drop. The system does much of the heavy lifting for you.
2. Long-Term Resilience
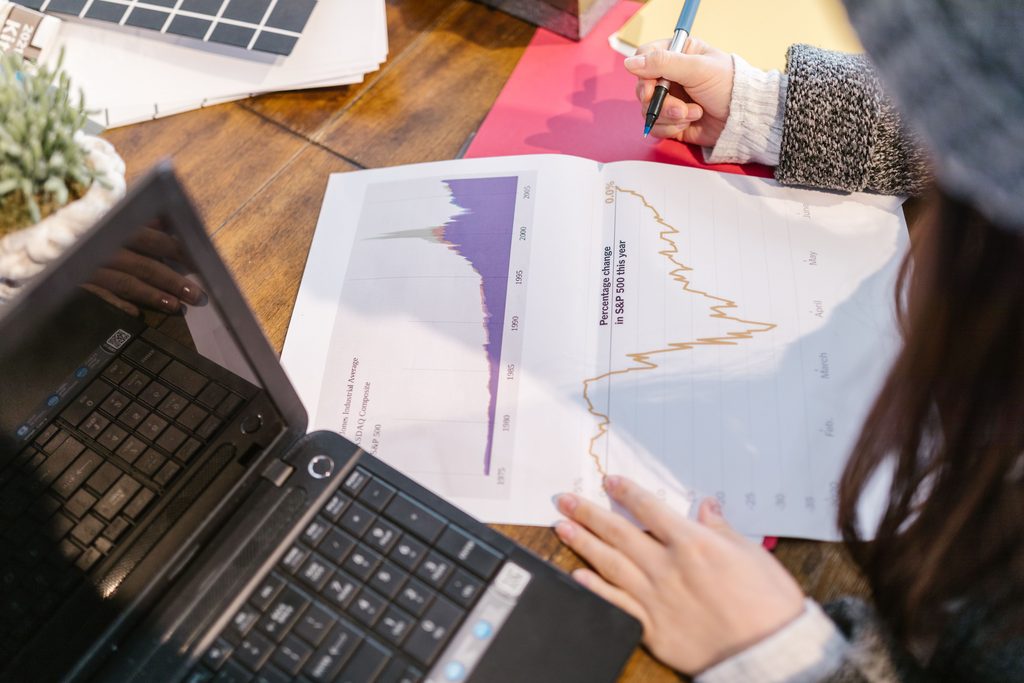
The American economy has lived through recessions, wars, high inflation, and a global pandemic. The S&P 500 has fallen hard in some of those periods. It dropped by more than 50% from its peak during the 2007–2009 financial crisis, and by about a third in just a few weeks in early 2020. Yet over long stretches it has recovered and reached new highs. Historically, the index has returned roughly 10% per year on average before inflation, and around 7% after inflation, over many decades.
Two honest caveats. First, that is an average, not a promise. Some years are strongly positive and some are painful. Second, past performance does not guarantee future results. The real lesson is about time: holding a broad fund for 10 or 20 years has historically been far more rewarding than jumping in and out. This is the same principle behind how compound interest builds wealth, where time does more of the work than the amount you start with.
3. Low Cost, High Efficiency
Because an S&P 500 fund simply tracks an existing list instead of paying a manager to pick stocks, its fees (called expense ratios) are tiny. Popular funds charge around 0.02% to 0.03% per year. That means about $2 to $3 per year on every $10,000 invested. Many actively managed funds charge 1% or more, which is 30 times higher or worse. Over decades, that gap can cost you tens of thousands of dollars. Low fees mean nearly every dollar you invest stays in your account to compound.
4. Automatic Dividends
Most companies in the index pay out a portion of their profits to shareholders as dividends. In most brokerage accounts, you can choose to have those dividends reinvested automatically to buy more shares. Over time, this adds meaningfully to your total return without any extra effort.
How to Buy the S&P 500, Step by Step
Getting started takes less time than a lunch break, and you do not need thousands of dollars to begin. If you want a slower walkthrough, see our full guide on how to buy your first index fund.
Step 1: Open a brokerage account. Choose a reputable, low-cost platform such as Fidelity, Charles Schwab, or Vanguard. These firms have no account minimums at most levels and strong customer protections. If you are navigating your financial setup with an ITIN rather than an SSN, policies differ by company, so check our roundup of the best ITIN investment apps for 2026 before you apply. You will also need a US bank account to link, and if you don’t have one yet, here is how to open a US bank account without an SSN.
Step 2: Fund your account. Link your checking account and transfer an amount you are comfortable with. Thanks to fractional shares and low-minimum funds, you can start with as little as $10 or $20 at many brokerages. If you are starting small, our guide to starting to invest in the US with $100 shows what is realistic.
Step 3: Search for an S&P 500 fund. Look up a popular ticker symbol (the short code that identifies a fund) in your brokerage search bar:
- VOO: Vanguard S&P 500 ETF
- IVV: iShares Core S&P 500 ETF
- SWPPX: Schwab S&P 500 Index Fund
- FXAIX: Fidelity 500 Index Fund
They all track the same index, and the differences between them are very small. Pick one and stay with it.
Step 4: Automate and forget. Set up a recurring monthly transfer so your investment happens automatically. This strategy, known as dollar-cost averaging, means you buy more shares when prices are low and fewer when they are high. It also removes emotion from the process. You stop trying to guess the “perfect” time to invest, which almost nobody can do consistently.
Where to Hold It: Think About the Account Type
The fund is only half of the decision. The account that holds it matters too. Retirement accounts such as a 401(k) or Roth IRA offer powerful tax advantages, and many employer plans already include an S&P 500 fund. Learn more in our posts on why every immigrant needs a Roth IRA and what a 401(k) is and whether you should use yours. If you plan to return home someday, it is also worth reading about US investments you can take with you anywhere.
The S&P 500 Has Limits, and You Should Know Them
No investment is perfect, and being honest about the downsides will make you a calmer investor.
- It can fall sharply. A drop of 20% or more has happened many times. If you might need the money within the next few years, it does not belong in the stock market.
- It is concentrated at the top. The index is weighted by company size, so the largest companies, mostly big tech firms, make up a large share of it. The top 10 holdings alone account for more than a third of the index. This means you are less diversified than “500 companies” sounds.
- It is US-only. If all your money is in one country’s stocks, you carry that country’s risk. Some investors add an international fund over time.
- It requires patience. The reward comes from staying invested through the ugly years.
Before You Invest: Protect Your Foundation
Stocks are for money you will not need soon. Before you put money into the S&P 500, make sure you have a small emergency fund in a savings account, and that you are not carrying high-interest credit card debt. If you are deciding between the two, read our comparison of index funds vs. high-yield savings, and where to put $1,000. Also review the common investing mistakes new immigrants make so you can avoid them from day one.
Frequently Asked Questions
How much money do I need to start? Many brokerages let you start with $1 to $10 using fractional shares, though some funds have higher minimums. You can begin small and increase over time.
Is the S&P 500 safe? It is diversified, but it is not risk-free. Your balance will go up and down, and you can lose money, especially over short periods.
Can I invest in the S&P 500 with an ITIN? Some brokerages accept ITINs, while others require an SSN. Rules change, so check directly with the provider.
Should I check my balance every day? The less often, the better. Frequent checking tends to lead to panic selling, which is one of the costliest mistakes new investors make.
Building Long-Term Security
You do not need to be a Wall Street millionaire to build wealth in America. By investing in the S&P 500 steadily, you are tying your financial future to the long-term growth of the broader economy, while you focus your energy on your family and career. Start small, automate it, and give it time.
Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice. All investing involves risk, including the possible loss of principal. Consult a qualified professional before making major financial decisions.